Roman Hauk
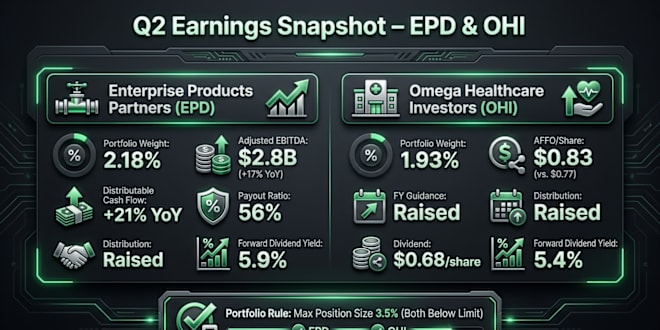
Two income names just confirmed why I hold them. $EPD (Enterprise Products Partners LP) is at 2.18% of the portfolio, $OHI (Omega Healthcare Investors Inc) at 1.93%, both comfortably under my 3.5% cap. Pretty boring quarter for both, in a good way, numbers moved the right direction. EPD's quarter was strong across the board, record EBITDA of $2.8 billion, up 17%, distribution raised again, payout still conservative at 56% with buybacks included. Forward yield around 5.9%, and honestly the 27-year streak does most of the talking here. OHI was the more interesting one. AFFO per share went from $0.77 to $0.83 and guidance got bumped up, dividend now $0.68, yield near 5.4%. Ignore the GAAP payout ratio if you look it up, it's a REIT accounting quirk, not a red flag. AFFO payout is a much more reasonable 82%. EPD still depends on volumes and execution, OHI on operator rent coverage. These two are already well represented in the portfolio relative to their performance and sector weight, so I'm glad to hold them and don't see a reason to add more on the next DCA round in two weeks.... ✌️😎
Not investment advice. The author may have financial interests in the mentioned instruments.
null
.