Eduard Torruella
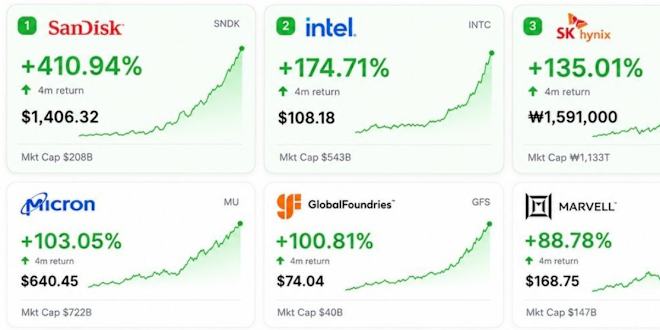
𝑾𝒉𝒂𝒕 π’Šπ’‡ π’Žπ’†π’Žπ’π’“π’š π’”π’•π’π’„π’Œπ’” 𝒂𝒓𝒆 𝒏𝒐𝒕 π’‚π’„π’•π’–π’‚π’π’π’š 𝒄𝒉𝒆𝒂𝒑… 𝒃𝒖𝒕 𝒄𝒍𝒐𝒔𝒆𝒓 𝒕𝒐 π’•π’‰π’†π’Šπ’“ π’“π’Šπ’”π’Œπ’Šπ’†π’”π’• π’‘π’π’Šπ’π’•? While studying for the CFA, I recently came across something called the Molodovsky effect, and I immediately thought about what we’re seeing today in memory stocks. The concept is simple: in cyclical industries, valuation multiples can be very misleading. When earnings are weak, stocks often look expensive on a P/E basis. But when earnings are exploding, usually near the top of the cycle, those same stocks can suddenly look β€œcheap”. Ironically, that’s often when risk is the highest. This feels very relevant today with names like $MU (Micron Technology, Inc.) $SNDK (Sandisk Corp/DE) $MRVL (Marvell Technology Group Ltd) or $SMSN.L (Samsung Electronics Co Ltd - GDR) . AI demand is clearly creating huge momentum around HBM, DRAM, and data center infrastructure. Pricing is strong, supply is tight, and earnings expectations keep moving higher. On the surface, some of these companies may even look attractively valued. But that’s exactly where investors need to be careful. If the market is valuing these businesses based on peak-cycle earnings, assuming today’s supply constraints and AI capex will continue for years, history suggests that could be dangerous. Memory has always been one of the most cyclical parts of semis. When supply eventually catches up, inventories build, or hyperscalers slow spending, margins can compress very quickly. That said, I don’t claim to know how this plays out. This bottleneck could last longer than expected, and the earnings environment could remain strong for an extended period. But what matters is recognizing that this setup is not risk‑free. Being aware of where we might sit in the cycle is just as important as the growth narrative itself.
Not investment advice. The author may have financial interests in the mentioned instruments.
1 reply
2 replies
1 reply
null
.