Roberto Anzellotti
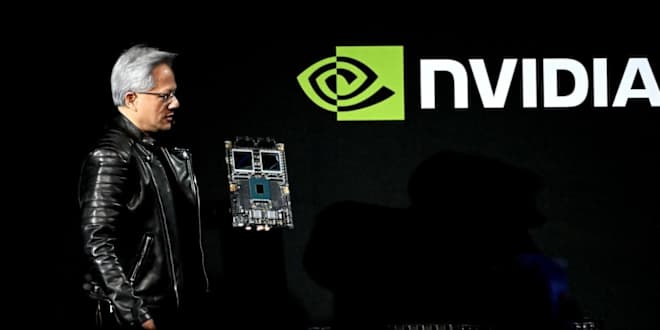
$NVDA (NVIDIA Corporation) ’S AI LEAD IS CLEAR. BUT HOW DURABLE IS IT? $NVDA is facing an interesting paradox: demand for computing power continues to grow, but the market is no longer satisfied with hearing about new data centers. It now wants to know whether those billions in CapEx will generate sustainable returns and how much of that value $NVDA will ultimately capture. Ahead of earnings on August 26, the numbers remain difficult to ignore. In Q1 FY27, revenue reached $81.6 billion, up 85% year over year; Data Center revenue rose to $75.2 billion, up 92%; non-GAAP gross margin remained at 75%, while free cash flow reached $48.6 billion. For the current quarter, management is guiding for approximately $91 billion in revenue, with margins still expected to remain around 75%. ✅ NVIDIA increasingly resembles an “AI utility” rather than a traditional chipmaker. GPUs, networking, complete rack-scale systems and, above all, CUDA create an integrated infrastructure that is difficult to replace. The acceleration of Vera Rubin, already being adopted by major cloud providers, confirms that NVIDIA’s competitive advantage now extends across the entire data center. ✅ Vera CPU and Rubin further expand the company’s addressable market. NVIDIA is not merely defending its position in GPUs: it is targeting server CPUs, agentic AI, robotics, digital biology and quantum computing. Vera Rubin promises up to 10 times greater performance per watt and lower token-processing costs than Blackwell, while management sees the CPU business approaching $20 billion in annual revenue. ✅ The valuation has also become less extreme. At current prices, NVDA trades at approximately 20–23 times forward earnings and close to 16 times expected FY28 earnings. The company has also authorized an additional $80 billion in share repurchases and increased its quarterly dividend from $0.01 to $0.25. The yield remains small relative to earnings, but it highlights NVIDIA’s growing capacity to return capital to shareholders. ✅ The risks have not disappeared: rising HBM and memory costs, power and construction constraints affecting data centers, custom chips developed by hyperscalers, Chinese competition and the financial sustainability of neocloud providers. Investments in companies such as Nebius strengthen NVIDIA’s ecosystem, but they also raise questions about whether part of AI demand is being financed from within the same industry loop. We do not need to predict how far artificial intelligence will run. We need to understand how much of that race will remain inside NVIDIA’s margins. For now, its advantage is clear; on August 26, we will find out how wide it still is. I am @IlMatematico and through Rules, Discipline and Time, I work every day to build a portfolio aimed at long-term financial serenity, both for myself and for those who choose to copy me, within a clear and structured long-term vision. Follow me to stay updated on my investment activity across $SPX500, $NSDQ100 and the crypto space.
Not investment advice. The author may have financial interests in the mentioned instruments.
null
.